You found your next home, but your current home hasn’t sold. https://www.youtube.com/watch?v=nbiYmoT09E8 A mortgage recast…
Over the USDA Income Limit? You Might Still Qualify
A household can appear to be over the USDA income limit and still qualify for a USDA home loan.
That is because USDA does not always compare a household’s total gross income directly against the published limit.
Before making that comparison, it applies specific deductions that can reduce the income used for eligibility.
This distinction matters.
A family earning a few thousand dollars above the USDA income limit may assume the program is off the table before looking at childcare costs, dependents, age-based deductions, medical bills, or disability-related expenses.
But those details can materially change the calculation.
The key is to separate gross household income from adjusted income. Gross income is the starting point.
Adjusted income is the number USDA uses after eligible deductions are applied.
For households close to the USDA income limit, that difference can be substantial.
❌ Gross Income Is Not Always the USDA Eligibility Number
When lenders evaluate the USDA income limit, they look at income from household members, not only the people applying for the loan.
That can include income from family members who will live in the property, even when they are not borrowers.
At first, this can make USDA qualification seem more difficult for multigenerational households or families with several working adults.
A parent moving in, an adult child contributing income, or multiple applicants may push gross income over the published county cap.
However, USDA then allows five deductions that can lower the household’s qualifying income.
The amount available depends on who lives in the home and the documented expenses the household actually pays.
That means being above the USDA income limit is not necessarily a final answer.
It is the beginning of a more detailed calculation.
1. The Dependent Deduction
The first deduction is for dependents.
USDA subtracts $500 for each eligible dependent in the household before determining whether the household is below the USDA income limit.
For this calculation, a dependent is a household member who is not the applicant, co-applicant, or spouse and who meets at least one of these conditions:
- Is age 17 or younger
- Lives with a disability
- Is a full-time student, regardless of age
This is often the easiest deduction to identify because many households already know who will live in the home.
Parents with young children may immediately have one or more qualifying dependents.
A full-time college student living at home could also qualify, even if that student is older than 17.
Consider a household with two children, ages eight and five.
Those two children create a $1,000 deduction from household income.
If the family starts only a few thousand dollars above the USDA income limit, the dependent deduction begins closing that gap right away.
To estimate this deduction, count every qualifying dependent in the future household and multiply that number by $500.
Subtract the result from gross annual household income.
2. The Child Care Deduction
USDA also provides a household deduction when an applicant, co-applicant, or spouse is age 62 or older.
The current deduction described here is $550 per household.
This is not a per-person deduction.
Even if two or three qualifying people are age 62 or older, the household receives one $550 deduction rather than $550 for each person.
For example, if a 68-year-old grandfather is a co-applicant, the household can receive the full deduction.
If the grandmother is also 65, the total remains $550. The household does not receive a second age-based deduction.
This is one of the most commonly missed details in a USDA income limit review.
Some buyers assume the older household member must be the primary income earner to matter.
That is not the issue.
If the person is an applicant, co-applicant, or spouse and is at least 62, the household may qualify for the deduction.
Age documentation should be included in the loan file so the deduction can be properly applied.
3. The Disability Assistance Deduction
USDA may allow a deduction for certain disability-related expenses when those costs help a household member work.
This deduction applies when a household member lives with a disability and pays the expenses out of pocket.
The calculation has an important limitation: only expenses above 3% of annual gross household income are deductible.
The entire expense is not automatically subtracted.
Here is how the math works:
- Start with the total eligible annual disability-related expenses.
- Calculate 3% of gross annual household income.
- Subtract the 3% threshold from the documented expenses.
- The remaining amount is the potential deduction.
Suppose a household earns $98,500 annually.
Three percent of that income is $2,955.
If the household spends $3,200 on a walker, a ramp, and accessibility modifications, the deductible amount is $245.
Eligible costs can include wheelchairs, ramps, home modifications, vehicle modifications, and equipment needed to support work.
Receipts and other documentation matter because the lender must verify both the expense and the out-of-pocket payment.
A $245 deduction may not seem large on its own.
But when a household is near the USDA income limit, every valid deduction can make a difference.
You can also combine this amount with the other four deductions.
4. The Medical Expense Deduction
The medical-expense deduction uses the same 3% threshold, but the total can be larger because healthcare expenses often add up quickly over a year.
If an elderly or disabled household member has unreimbursed medical expenses, USDA may deduct the portion above 3% of gross annual income.
“Unreimbursed” means the household paid the cost and was not repaid by insurance or another source.
Expenses may include:
- Prescription medications
- Doctor visits
- Home health care
- Medical treatment paid out of pocket
- Insurance premiums not already deducted through payroll
Using the same $98,500 household-income example, the 3% threshold remains $2,955.
If prescription costs, medical visits, and home-health assistance total $4,200 for the year, the possible deduction is $1,245.
The formula is:
Total unreimbursed eligible medical expenses − 3% of gross annual household income = potential medical deduction.
Retain medical records, bills, premium statements, receipts, and proof of payment.
Families trying to qualify under the USDA income limit should not leave these expenses in a drawer or assume they do not matter.
Accurate documentation may help turn an apparent denial into an eligible file.
5. Income Earned by a Minor
For many working families, childcare is the most important deduction in the USDA calculation.
USDA may deduct the full cost of childcare for children age 12 and under, as long as the care allows a household member to work, seek employment, or attend school.
Unlike medical and disability-related costs, childcare has no percentage threshold.
It also does not have the same type of cap.
If the expense is eligible and documented, the full annual amount can reduce qualifying income.
Imagine parents paying $650 each month for after-school care for two children so they can keep working.
That is $7,800 per year.
Under the stated rules, the entire $7,800 can be deducted from household income for USDA eligibility.
This deduction is particularly meaningful for families who narrowly exceed the USDA income limit.
It can be much larger than the dependent deduction and may be the difference between being over the cap and falling well below it.
Childcare also does not count as debt in the borrower’s debt-to-income ratio.
That means it can help reduce adjusted income for USDA eligibility without being treated like a monthly loan payment.
Documentation should include provider receipts or statements, evidence that the household pays for care, and proof of the child’s age.
The provider does not have to be licensed. However, childcare payments to a household member do not qualify for this deduction.
🤝 How the Five USDA Deductions Work Together
The power of these rules becomes clearer when you stack the deductions.
Consider a multigenerational household with $98,500 in gross annual income and a county USDA income limit of $95,000.
At first glance, the household is $3,500 over the limit.
But the household has two young children, one co-applicant over age 62, disability-related expenses, medical expenses for an elderly household member, and work-related after-school care:
- Two dependent children: $1,000 deduction
- One applicant or co-applicant age 62 or older: $550 deduction
- Eligible disability-related expenses: $245 deduction
- Eligible unreimbursed medical expenses: $1,245 deduction
- Work-related childcare expenses: $7,800 deduction
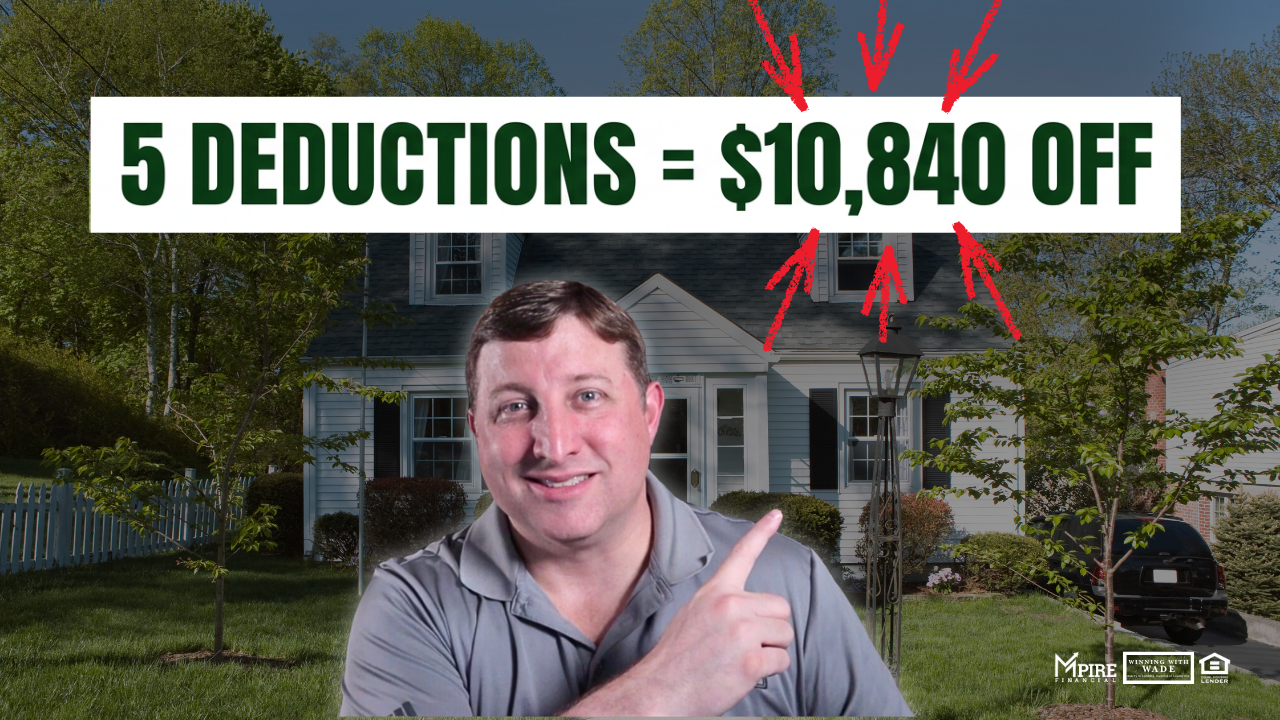
The total deduction is $10,840.
Subtracting that amount from $98,500 leaves adjusted income of $87,660. Instead of being $3,500 above the county limit, the household lands more than $7,000 below it.
Every household’s numbers will be different.
The point is not that every family above the USDA income limit will qualify.
The point is that gross income alone does not always tell the full story.
USDA Income Limit Checklist
If your household appears close to or above the USDA income limit, gather the details before assuming USDA is unavailable:
- List everyone who will live in the home.
- Identify dependents age 17 and under, full-time students, and disabled household members.
- Confirm whether an applicant, co-applicant, or spouse is age 62 or older.
- Collect receipts for disability-related expenses that support work.
- Organize unreimbursed medical bills for elderly or disabled household members.
- Total annual childcare costs for children 12 and under.
- Verify that childcare enables work, job searching, or school attendance.
- Keep statements, receipts, and proof of payment for every claimed expense.
Do this before making major decisions about where to buy or which loan program to pursue.
A proper USDA income limit review depends on the household composition, income sources, deductions, and documentation, not a quick comparison of a salary against a county chart.
📣 Frequently Asked Questions (FAQs)
Can I qualify if my income is above the USDA income limit?
Possibly. USDA may apply deductions for dependents, elderly household members, qualifying disability expenses, eligible medical costs, and childcare before comparing adjusted income with the limit.
Does USDA count income from everyone living in the home?
USDA household-income calculations can include income from household members beyond the applicants. That is why a full household review is important.
How much is the USDA dependent deduction?
The dependent deduction is $500 for each eligible household member who is not an applicant, co-applicant, or spouse and meets the dependent criteria.
Are all medical bills deductible for USDA eligibility?
No. The deduction applies to eligible unreimbursed medical expenses for elderly or disabled household members, and only the amount above 3% of gross annual household income may count.
Does childcare affect my debt-to-income ratio?
Childcare is not counted as debt in the debt-to-income ratio. Eligible childcare costs may still be fully deducted from income for USDA eligibility purposes.

About the Author
Wade Betz
Mortgage Broker at Winning WIth Wade · NMLS #280613
Wade has been a stalwart in the mortgage industry since 2006, dedicating himself to helping thousands of families navigate the complexities of home financing. With so much experience, he stands out as a leading mortgage originator in the Dallas-Fort Worth area.
Specializes in: DSCR Loans, VA Loans, Reverse Mortgages
Licensed in: AL, AZ, AR, CA, CO, CT, FL, GA, ID, IL, IN, KS, LA, MD, MI, MS, MT, NE, NJ, NM, NC, OH, OK, OR, PA, SC, TN, TX, VA, WA, WI
Related Posts