You found your next home, but your current home hasn’t sold. https://www.youtube.com/watch?v=nbiYmoT09E8 A mortgage recast…
How to Find VA Approved Condos
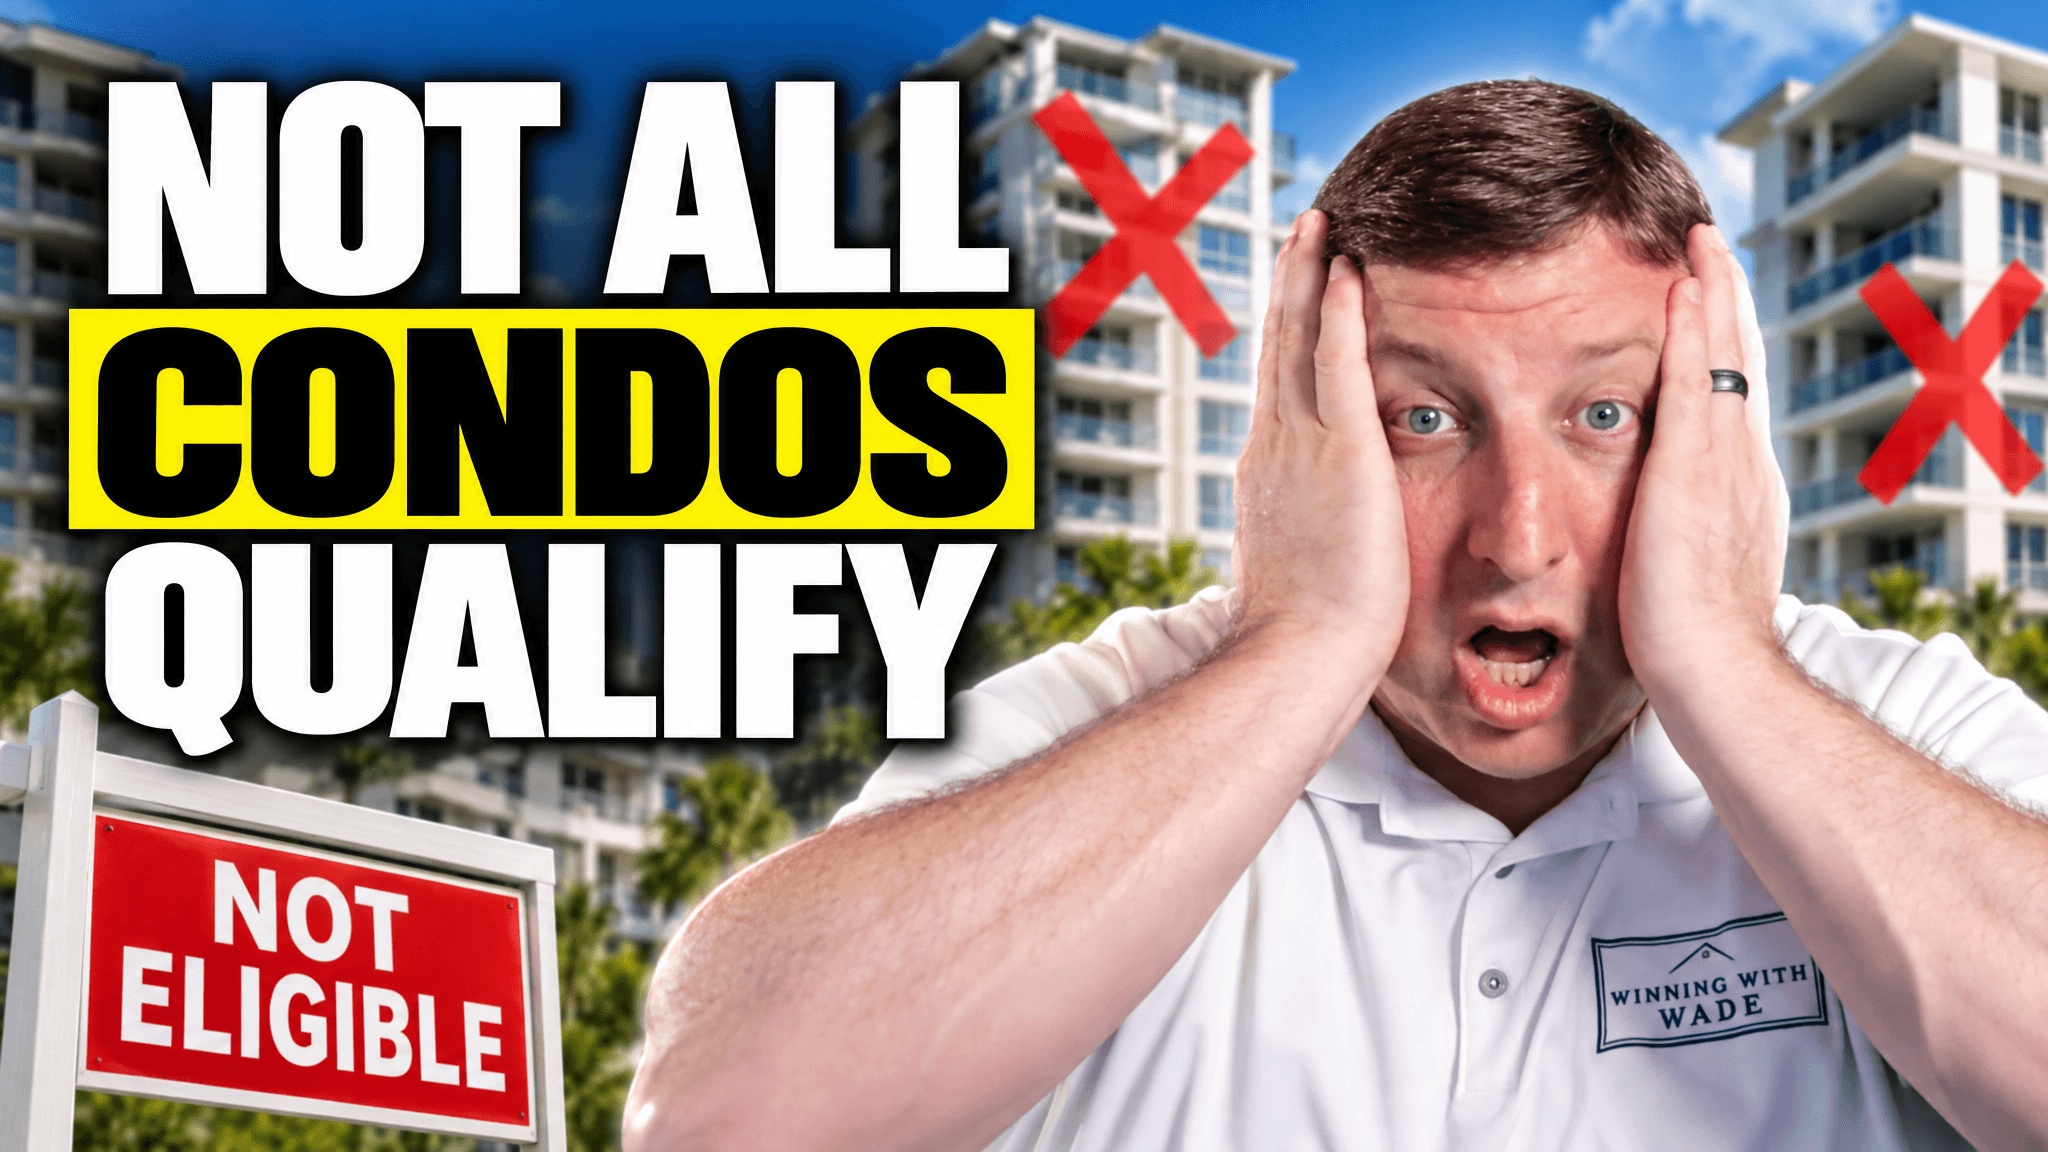
Buying a condo with a VA loan is possible, but finding VA approved condos comes with one requirement that catches veterans off guard more than almost anything else in the process.
The condo project itself has to be on the VA approved list before the loan can close.
Most buyers assume that if they qualify for a VA loan and can afford the unit, the financing will work.
With condos, that assumption can fall apart three weeks into a contract when the lender discovers the building is not among the VA approved condos in the area and there is no clear path to get it listed before the closing deadline.
Knowing how to check the VA approved condo list before making an offer, what options exist when a building is not listed, and how the approval process works gives veterans a real advantage before they start shopping.
🇺🇸 Why VA Condo Approval Works Differently
Every major loan program has rules for condos, but VA handles it differently from conventional and FHA financing.
Fannie Mae and Freddie Mac allow lenders to conduct their own project reviews through internal systems.
FHA maintains an approved condo list but also offers a single-unit approval process that lets lenders approve one unit at a time, even when the full project isn’t on the list.
VA requires the entire condo project to be on the VA approved list before a veteran can purchase any unit in that building using VA financing.
VA has no equivalent to FHA’s single-unit approval.
When the building isn’t on the list, the veteran must either pursue project approval or choose a different unit in a different building.
This rule matters most for veterans shopping for condos in North Texas.
How to Check the VA Approved Condo List
The VA approved condo list is publicly searchable through the VA’s online system called WebLGY.
Veterans and their agents can search by state, county, or project name to see whether a specific building is approved.
Steps to check a building:
- Go to the VA’s WebLGY portal
- Search by state and county or enter the condo project name
- Review the project status shown in the results
- Confirm the approval is current and has not expired or been withdrawn
Each listing shows the project name, location, and current approval status.
An approved status means VA financing is available for units in that building.
A status of rejected, withdrawn, or not found means VA financing is not currently available, and pursuing the loan on that unit will require additional steps.
Checking the list before writing an offer takes minutes and can save weeks of wasted time, inspection costs, and emotional investment in a unit that cannot support VA financing.
✅ What the Approval Status Categories Mean
When searching WebLGY, the project status will fall into one of several categories:
- Approved: The project meets VA requirements and VA financing is available for eligible units
- Rejected: The project was reviewed and did not meet VA requirements; VA financing is not available
- Withdrawn: The approval was voluntarily withdrawn, typically by the HOA or management company
- Expired: A prior approval lapsed and has not been renewed
- Not found: The project has never been submitted for VA review
Rejected and not found are the two most common situations veterans encounter when shopping condos in active North Texas markets like Frisco, Plano, Irving, and Dallas.
What to Do When the Building Is Not VA Approved
A building that is not on the VA approved list is not automatically off the table.
You can take steps to pursue approval, though the process takes time and the outcome is not guaranteed.
Request a VA condo project approval
The lender or the HOA can submit the project for VA review.
The submission requires a package of documents from the HOA including:
- The condo declaration and bylaws
- HOA budget and financial statements
- Reserve fund balance and reserve study
- Proof of adequate master insurance coverage
- Information on owner occupancy and investor concentration
- Any pending or active litigation involving the project
- HOA meeting minutes from recent periods
VA reviews the submission and determines whether the project meets its requirements.
When approved, the project is added to the WebLGY list and VA financing becomes available for eligible units.
The challenge is timing.
A purchase contract typically has a defined closing window, and VA project approval can take weeks or longer depending on the completeness of the HOA submission and VA’s current review volume.
Veterans should not go under contract expecting approval to happen in time unless the lender has assessed the timeline and confirmed it is realistic.
Use a different loan program
When VA approval isn’t feasible within the transaction timeline, a veteran may still be able to purchase the unit with conventional financing if the project meets Fannie Mae or Freddie Mac standards.
FHA single-unit approval may also be an option if the project meets FHA requirements.
Switching loan programs affects the down payment requirement, mortgage insurance structure, and overall loan cost.
A veteran giving up the VA benefit to use conventional or FHA financing to purchase a specific condo should weigh those trade-offs carefully before proceeding.
Choose a VA approved building
The most straightforward path is finding a condo in a building that is already on the VA approved list.
In North Texas, many condo projects across Dallas County, Collin County, Denton County, and Tarrant County carry active VA approval.
Searching WebLGY before starting the condo search, rather than after finding a unit, filters options to buildings where VA financing is already available.
❌ Why Some Buildings Are Not on the VA Approved List
A building may be absent from the VA approved list for several reasons, and understanding why helps veterans evaluate whether pursuing approval is realistic.
Common reasons a project is not approved include:
- The HOA has never submitted the project for VA review
- A prior approval expired and was not renewed
- The project was reviewed and rejected due to financial issues, litigation, or owner occupancy concerns
- The reserve fund balance does not meet VA requirements
- Too high a percentage of units are investor-owned rather than owner-occupied
- Active litigation involving the project’s physical condition or finances
When a project was rejected rather than never submitted, finding out why matters.
A project rejected for financial reasons or active litigation is unlikely to be approved on a second submission until those issues are resolved.
How VA Condo Requirements Compare to Other Programs
VA, FHA, and conventional financing all evaluate condo projects, but the standards and processes differ in ways that affect which buildings are available to each type of buyer.
Owner occupancy
VA does not have a published minimum owner-occupancy requirement like FHA.
Still, VA reviewers consider the project’s overall financial health and stability, which can be affected by high investor concentration.
Reserve funds
VA requires the HOA to maintain adequate reserves to cover future maintenance and repairs.
The standard is similar to conventional requirements, but VA reviewers may evaluate it differently.
Litigation
Active litigation involving the project’s physical condition or finances can prevent VA approval.
This applies to FHA and conventional as well, but the threshold and review process differ by program.
Single unit approval
FHA offers single-unit approval, which allows financing on one unit even when the full project is not on the FHA approved list.
VA has no equivalent. The entire project must be approved for any unit to be eligible for VA financing.
🛠️ VA Condo Approval for New Construction
Veterans purchasing a newly built condo face an additional layer of complexity.
VA generally requires that at least 70% of units in a new condo project be sold before the project can be approved for VA financing.
Many new developments do not meet that threshold during the early sales phases.
A veteran who falls in love with a unit in a brand-new building may find VA financing unavailable until the development reaches sufficient sales volume, which could be months or years away.
Checking the sales status of a new development before going under contract prevents a situation where the purchase timeline and the VA approval timeline are fundamentally incompatible.
The VA approved condo list exists to protect veterans from buying into projects with financial problems that could affect their ability to sell, refinance, or maintain their home down the road. Check the list before you write the offer, not after.” — Wade Betz, Winning With Wade | Mortgage Education and Strategy
Working With Your Agent and Lender on VA Condo Searches
A real estate agent who works regularly with VA buyers should know to check WebLGY before showing condo units.
An experienced VA lender should be able to pull the project status within minutes of receiving a property address.
If you work with an agent or lender unfamiliar with the VA condo approval process, you may need to take the initiative.
Asking the agent to confirm VA approval status before scheduling showings and asking the lender to pull the WebLGY status before writing an offer adds one step that can prevent a far more costly problem later.
If a lender is not familiar with how to submit a condo project for VA approval or how to evaluate whether a project is likely to be approved, that is worth knowing before relying on them for a condo purchase.
✅ VA Approved Condo Checklist
Before writing an offer on a condo:
- Search the building on WebLGY and confirm the current approval status.
- If approved, confirm the approval has not expired or been withdrawn.
- If not approved, ask the lender whether the project can be submitted for review within the expected closing timeline.
- Ask the HOA or listing agent whether the project has previously been submitted for VA review and what the outcome was
- Confirm the reserve fund balance and whether active litigation exists.
- For new construction, confirm the percentage of units already sold.
- If VA approval is not feasible, evaluate conventional or FHA financing as alternatives and compare the full cost of each option.
📣 Frequently Asked Questions (FAQs)
Do all condos qualify for VA financing?
No. The condo project must be on the VA approved list before a veteran can purchase a unit using VA financing. A unit in an unapproved building is not eligible for a VA loan, regardless of the veteran’s personal qualifications.
How do I check if a condo is VA approved?
Search the VA’s WebLGY system using the state, county, or project name. The system shows the current approval status for each listed project.
Can a condo be added to the VA approved list?
Yes. The lender or HOA can submit the project for VA review. The submission requires a comprehensive package of HOA documents, including financial statements, reserve fund information, insurance documentation, and information on litigation and owner occupancy.
How long does VA condo approval take?
The timeline varies based on the completeness of the submission and VA’s current review volume. The process can take several weeks or longer, which may not align with a standard purchase contract timeline.
Does VA have a single-unit approval like FHA?
No. VA requires approval of the entire condo project before any unit in that building is eligible for VA financing. VA has no equivalent to FHA’s single-unit approval process.
What happens if VA previously rejected the building?
You can resubmit a rejected project, but you must resolve the underlying issues that caused the rejection first. A project rejected for financial problems, inadequate reserves, or active litigation is unlikely to be approved on resubmission until those issues are addressed.
Can a veteran use conventional financing if the condo is not VA approved?
Yes. If the project meets Fannie Mae or Freddie Mac standards, conventional financing may be available. The veteran would need to meet conventional down payment and qualification requirements and would not have access to the VA benefit for that transaction.
Are new construction condos eligible for VA financing?
VA generally requires that at least 70% of units in a new condo project be sold before it can approve the project. Many new developments do not meet this threshold during early sales phases, which can make VA financing unavailable until the project reaches sufficient sales volume.

About the Author
Wade Betz
Mortgage Broker at Winning WIth Wade · NMLS #280613
Wade has been a stalwart in the mortgage industry since 2006, dedicating himself to helping thousands of families navigate the complexities of home financing. With so much experience, he stands out as a leading mortgage originator in the Dallas-Fort Worth area.
Specializes in: DSCR Loans, VA Loans, Reverse Mortgages
Licensed in: AL, AZ, AR, CA, CO, CT, FL, GA, ID, IL, IN, KS, LA, MD, MI, MS, MT, NE, NJ, NM, NC, OH, OK, OR, PA, SC, TN, TX, VA, WA, WI
Related Posts